Moving overseas can change almost every part of daily life, from employment and banking to residency and financial planning. For some Americans, however, one important obligation can be overlooked: continuing to meet U.S. tax filing and reporting requirements.
U.S. citizens and resident aliens generally remain subject to U.S. federal tax rules on worldwide income even when they live outside the country. Living abroad does not automatically eliminate the requirement to file a U.S. tax return or address foreign financial reporting obligations.
If several years have passed without filing, the situation can understandably feel overwhelming. The first step, however, is not to panic. It is to understand what was missed, gather the necessary information, and determine which compliance procedures may apply.
Why Do Americans Abroad Fall Behind?
There are many reasons an American living overseas may become behind on U.S. tax filings.
Some people genuinely do not realise that U.S. citizens can continue to have federal filing obligations after moving abroad. Others may assume that paying tax in their country of residence eliminates the need to file in the United States.
Foreign financial reporting can create another source of confusion. An individual may know about the annual income tax return but not realise that foreign bank accounts could create a separate FBAR requirement. Similarly, certain foreign financial assets may need to be reported under FATCA rules.
Business owners can face additional complexity if they establish a foreign corporation, partnership, or other entity. The resulting information reporting can be considerably more complicated than a standard individual tax return.
Start by Gathering Your Records
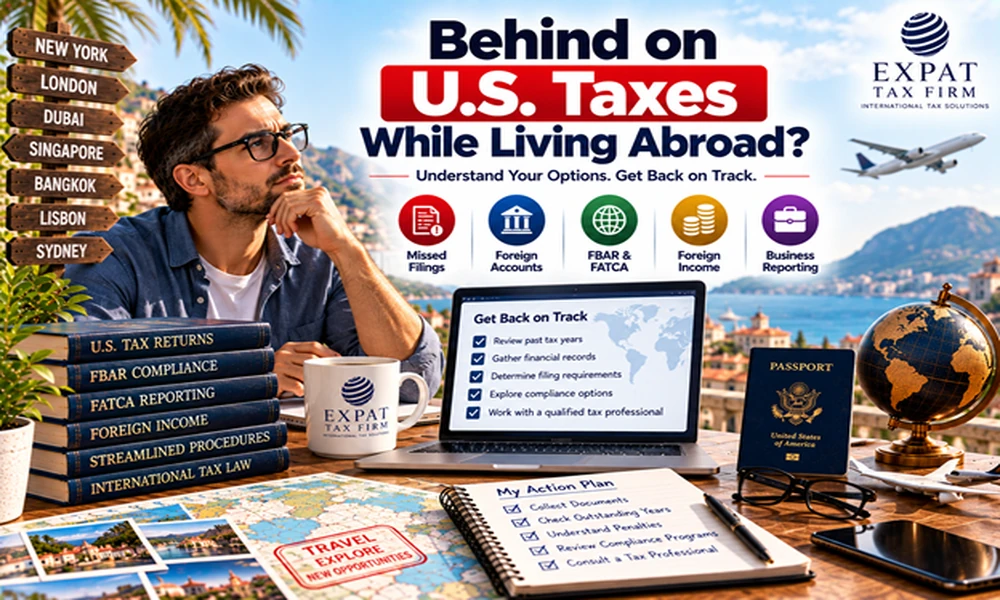
Before attempting to catch up, it is useful to assemble as complete a financial history as possible.
Depending on your circumstances, this could include:
- Previous U.S. tax returns
- Foreign employment records and payslips
- Foreign bank statements
- Investment and brokerage statements
- Pension or retirement records
- Foreign tax returns
- Records of taxes paid overseas
- Business financial statements
- Foreign company ownership documents
- Property and rental records
- Information about foreign trusts or other entities
- Currency conversion records
Foreign bank statements are particularly important because you may need to determine the highest balance in qualifying accounts during each relevant year for FBAR purposes.
If records are missing, contact the relevant financial institution or employer rather than estimating figures without documentation.
Determine What You Actually Owe and What Must Be Reported
Being behind on filing does not necessarily mean that you owe a large amount of U.S. tax.
Your final position depends on your income, deductions, credits, foreign taxes, filing status, and other circumstances. Eligible Americans abroad may also have access to provisions such as the Foreign Earned Income Exclusion or Foreign Tax Credit, depending on their facts.
However, income tax is only part of the analysis.
You may also need to determine whether FBARs, Form 8938, or other international information returns were required. The IRS has separate reporting rules for various foreign financial assets and business interests, and penalties can apply when required information returns are not filed correctly.
The objective should therefore be to establish your complete compliance position rather than simply preparing an overdue Form 1040.
What Happens With Late Returns?
Generally, taxpayers who have missed required U.S. returns need to determine which tax years remain outstanding and prepare the appropriate returns.
Late filing can result in penalties and interest when tax was due. The IRS explains that penalties can apply for failure to file, failure to pay, and certain inaccurate or incomplete information returns.
There can be circumstances in which penalty relief is available, including certain situations involving reasonable cause or specific IRS administrative relief. However, eligibility is fact-specific and should not be assumed simply because someone lives overseas.
For that reason, an American who is several years behind should evaluate the circumstances before deciding how to submit delinquent returns.
Streamlined Filing Compliance Procedures
Some Americans living abroad may qualify for the IRS Streamlined Foreign Offshore Procedures.
These procedures are designed for eligible taxpayers whose failure to report income, pay tax, or submit required information returns and FBARs resulted from non-willful conduct. The IRS defines non-willful conduct in this context as conduct resulting from negligence, inadvertence, mistake, or a good-faith misunderstanding of the law.
For eligible taxpayers living outside the United States, the streamlined foreign procedures generally involve filing the most recent three years of delinquent or amended tax returns and the most recent six years of delinquent FBARs for which the relevant deadlines have passed, along with required certifications and information returns.
Importantly, not every taxpayer who is behind automatically qualifies. The IRS has specific eligibility requirements, and taxpayers should carefully evaluate whether their circumstances meet those requirements.
Taxpayers whose conduct may have been willful, or who are already subject to certain IRS examinations or investigations, may require a different approach.
What About Delinquent Information Returns?
A taxpayer may discover that the problem involves more than unfiled income tax returns.
For example, a foreign business interest might require an information return, or a foreign financial asset might trigger Form 8938 reporting. The IRS provides separate procedures for certain delinquent international information returns. Penalties may apply, although taxpayers may have options to explain circumstances such as reasonable cause where applicable.
This is why reviewing the complete history before filing is important. Submitting one missing form does not necessarily resolve every outstanding international reporting requirement.
Why Professional Advice May Be Appropriate
International tax compliance can involve several overlapping systems. A taxpayer may have U.S. income tax obligations, foreign income, overseas bank accounts, investments, property, and perhaps a foreign business.
A professional familiar with international taxation can help organise the available records, identify potentially missing forms, assess which compliance procedure may be appropriate, and distinguish between tax liabilities and information-reporting obligations.
Expat Tax Firm publicly lists services including Streamlined Filing Compliance, late tax return preparation, FBAR filing, FATCA compliance, foreign income reporting, foreign corporations, and small business compliance.
The firm identifies Mitchell Propster as its founder and its team page identifies him as Mitch, CTC, Team Leader. Americans researching professional resources for international tax matters can also review Mitchell Propster’s LinkedIn profile.
A Practical Starting Point
If you are behind on U.S. taxes while living abroad, start by building a timeline.
List the years you lived outside the United States, where you lived, what income you received, which foreign accounts you held, whether you owned foreign businesses or property, and which U.S. returns you filed.
Then gather the supporting records and determine which obligations remain outstanding.
Most importantly, avoid assuming that living abroad automatically excuses missed filings or that a particular compliance program will eliminate penalties. The appropriate solution depends on the facts of the individual case.
Taking the time to understand the complete situation can make the process more organised and provide a clearer path toward bringing past U.S. tax and reporting obligations up to date.
Disclaimer: This article is for general educational purposes only and does not constitute tax, legal, accounting, or financial advice. Late filing procedures, penalty rules, and eligibility for specific IRS compliance programs depend on individual circumstances. Taxpayers who are behind on U.S. filings should consult the IRS and, where appropriate, a qualified international tax professional before taking action.